
Melamine Plywood Export Market Watch: Amid Diverging Demand, Quality and Local Adaptation Stand as Core Competitiveness
As an engineered wood panel combining structural stability and pre-finished decorative surfaces, contraplacado de melamina has long been a mainstream material for global furniture manufacturing, interior fit-out and commercial exhibition sectors. Unlike ordinary plywood that requires secondary surfacing, it is manufactured by hot-pressing melamine-impregnated paper onto the wood substrate. The finished panels come with wear-resistant, stain-proof and colourfast decorative layers, which greatly simplify cutting and assembly processes for downstream users. This meets overseas buyers’ needs to cut operational costs and shorten lead times. Against the backdrop of continuous home renovation and commercial space upgrading worldwide, exports of this product remain steady, while shifts in demand structure, procurement standards and competition logic keep unfolding.
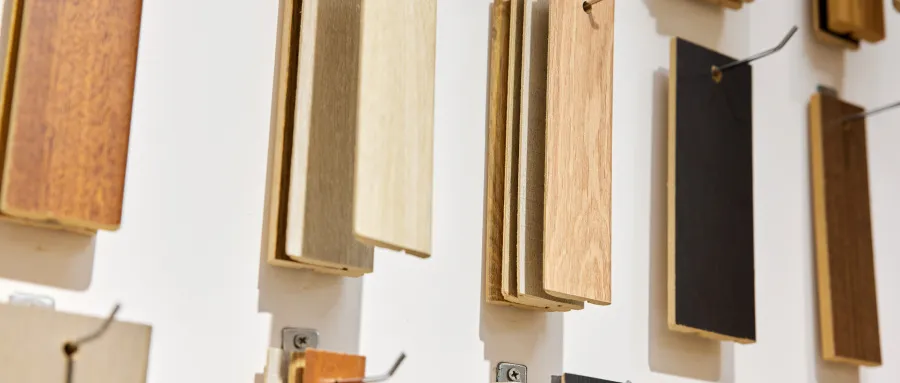
In terms of product features, the cross-laminated veneer core delivers good resistance to warping. Compared with MDF and particleboard of the same specification, it offers superior screw holding capacity and moisture resistance, suitable for indoor environments with fluctuating humidity. Melamine finishes are available in solid colours, wood grains, stone patterns and other designs, with matte, soft-gloss and embossed textures to match diverse aesthetic preferences across regions. The standard export size is 4×8 ft, with thickness ranging from 6 mm to 25 mm. Panels of 9–18 mm are the most widely adopted for cabinet bodies, wardrobes, commercial shelving and fixed furniture in hotels. For high-moisture spaces such as kitchens and laundry rooms, buyers tend to select grades with moisture-resistant adhesive systems to reduce risks of delamination and swelling. As a pre-finished no-paint product, it eliminates on-site spraying work and reduces construction-related emissions, making it a preferred option for purchasers prioritising indoor environmental performance.
Global demand shows clear regional divergence. Buyers in mature markets tend to pursue refined and compliant products. Their purchase requirements cover formaldehyde emission standards, surface wear rating, core void content and thickness tolerance, and orders are often accompanied by complete test documents and traceability records. New colour trends closely follow local interior design styles, and small-batch orders with custom finishes are on the rise. Growth in emerging markets mainly comes from residential construction, retail store fit-outs and public facility renovation. Buyers in these markets focus more on reliable supply and cost balance, with solid white and classic wood grain panels recording higher sales volume. Downstream application preferences also vary: a large share in Europe and North America goes to custom cabinetry and built-in storage systems; demand in the Middle East and Southeast Asia stays stable for display fixtures and hotel guestroom furniture; buyers in Oceania pay close attention to documentation verifying sustainable wood sourcing.
Compliance requirements have become a non-negotiable prerequisite for exports. Formaldehyde emission is a key indicator inspected by all buyers, and failure to meet relevant limits will hinder customs clearance and end-market distribution. Beyond emission tests, assessments on raw material traceability, wear resistance, resistance to household chemicals and dimensional stability are increasingly included in batch sampling inspections. Many importers require test reports to accompany shipments, with consistent information across documents, panel markings and laboratory data. Compliance is no longer viewed as an added advantage but a basic entry requirement. With equivalent pricing, suppliers with complete and consistent test records are more likely to secure long-term partnerships. This pushes supply chains to upgrade quality control, shifting focus from surface appearance only to full-process management covering raw veneers, adhesives, hot-pressing and warehousing.
The competitive landscape is diversified, and room for competition based purely on low pricing continues to shrink. End buyers are shifting focus from unit price to total cost of use, including surface flatness, edge-banding compatibility, chipping risk during cutting and colour consistency across batches. Many furniture manufacturers report that surface defects, colour variation and warping directly raise processing waste, offsetting savings from lower prices. Differentiated product lines therefore create separate market niches: low-emission premium grades for high-end interior projects, moisture-resistant variants for humid environments, and standardised panels with fixed colours and stable lead times for chain brand clients.
Overall, the contraplacado de melamina export market has moved past the phase of volume-driven growth. Consistent quality, complete compliance documentation, application-specific specifications and dependable delivery form the foundation of competitive advantage. For suppliers, understanding the practical pain points of buyers in different regions, implementing clear product grading and stable quality management will support steady expansion in overseas markets amid fragmented demand.